Damage and policy limits
Cosmetic restrictions, roof settlement endorsements and a wind/hail deductible can change payment. A roof needing work does not by itself establish a covered loss.
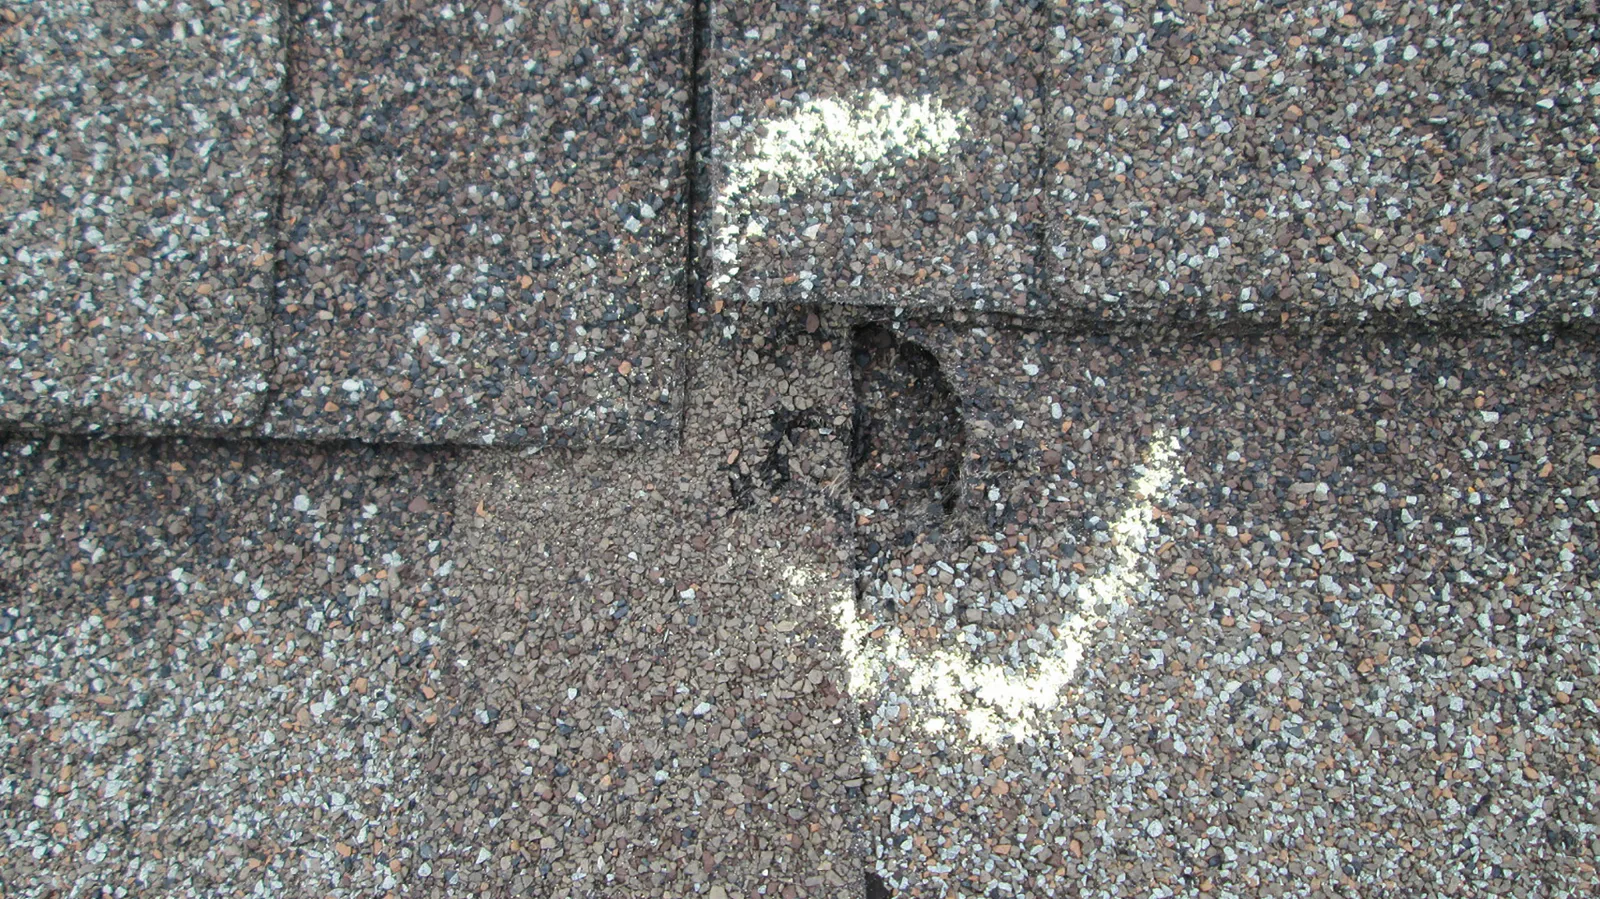
Understand deductibles, actual cash value, replacement-cost coverage and how roof work differs from a claim decision.
A roofing price describes the work. An insurance settlement follows the policy, the cause of loss and the claim decision. Understanding that distinction helps explain the amount an owner may still pay.
The roofing price is separate from the insurer’s settlement.
Deductible, depreciation, exclusions and chosen upgrades can affect what the owner pays.
The Oklahoma Insurance Department roof-claim FAQs explain depreciation and roof settlement types. The actual policy and endorsements control your claim.
| Term | Practical meaning |
|---|---|
| Deductible | The owner’s portion under the policy. Wind/hail can have a separate deductible. |
| Actual cash value | Payment reflects depreciation under the policy settlement terms, rather than assuming the full replacement price. |
| Replacement-cost coverage | Additional payment can depend on completed or contracted repair/replacement and the policy’s conditions. |
| Recoverable depreciation | An amount held back that is recoverable only when the policy conditions are met. Not all depreciation is recoverable. |
The roof work and claim record need to remain clear about what each step establishes.
Temporary protection is separate from permanent rebuilding. Keep records of work and condition associated with the concern.
An inspection identifies visible condition and useful work. It does not guarantee an insurer’s cause or coverage decision.
Report the concern promptly to the insurer and follow the policy’s requirements. The insurer’s inspection and decision determine the covered scope.
The contractor’s roofing scope and the insurer’s loss scope can differ. Deductible, depreciation, exclusions and chosen upgrades affect owner cost.
OID’s wind and hail guidance explains that policy limitations can affect roof claims.
Cosmetic restrictions, roof settlement endorsements and a wind/hail deductible can change payment. A roof needing work does not by itself establish a covered loss.
Some insurers offer benefits for eligible impact-resistant products. The actual insurer and policy determine eligibility, so a shingle rating does not establish a premium reduction.
Age or a leak alone does not establish coverage. The cause, policy terms and claim assessment control.
No. A report records an event at a location and time. Property findings and history are needed for the actual roof.
No. The price describes the agreed work. The insurer applies the policy, deductible and settlement terms to the loss.
Start with the roof condition. Request a free inspection for storm-related concerns, then consider the roofing scope alongside the actual insurance terms.